Malta Adopts Tiered Gaming Tax Framework for Local Operators Effective October 2026
Viktor Coleman · Sep 26, 2026
Malta Adopts Tiered Gaming Tax Framework for Local Operators Effective October 2026
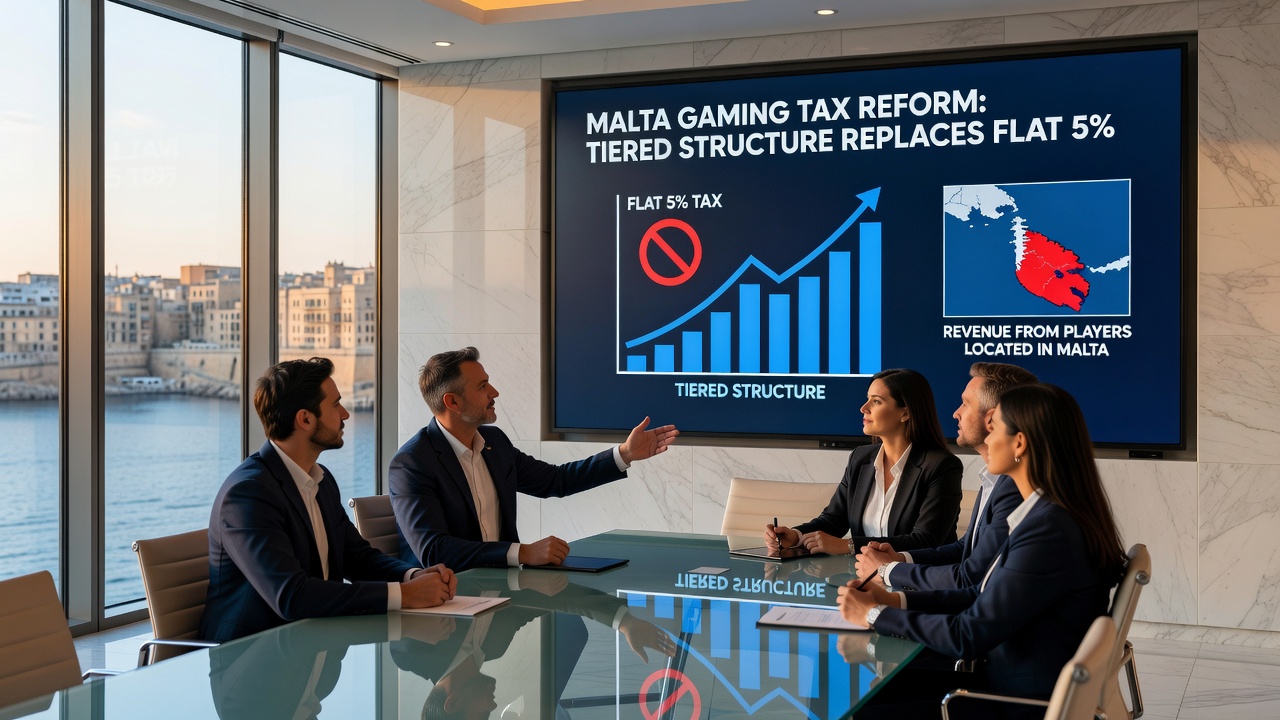
Malta will replace its flat 5% gaming tax on revenue from players located in Malta with a tiered structure starting October 1, 2026, and the Gaming Tax (Amendment) Regulations enact this shift while also abolishing the separate gaming device levy. The new rates stand at 15% on casino games and Type 1 services including RNG and lotteries, whereas betting, poker, and bingo under Type 2-4 services face 10% instead, and observers note that these changes target only domestic players so international revenue remains unaffected.
Details of the Tax Reform
The Gaming Tax (Amendment) Regulations, 2026, amend the existing Gaming Tax Regulations S.L. 583.10 through Legal Notice 84 of 2026, and this legislation narrows VAT exemptions as part of broader updates to the jurisdiction’s fiscal framework for both remote and land-based gaming. Those who have tracked Malta’s gaming sector over the years recognize that the previous flat rate applied uniformly, yet the tiered approach now differentiates by service type, which means operators must categorize their offerings accordingly starting in the fourth quarter of 2026.
Research from regulatory filings shows the reform applies exclusively to revenue generated from players situated in Malta, while operators continue to handle international markets under the prior structure without alteration. Experts have observed that this domestic focus aligns with efforts to refine the local tax base, and the abolition of the gaming device levy removes an additional layer that previously affected certain equipment used in land-based operations.
Service Classifications and Rate Application
Type 1 services encompass casino games along with RNG-based products and lotteries, which now incur the higher 15% rate, whereas Type 2 through Type 4 cover betting activities, poker, and bingo at the 10% level. Data indicates that operators will need to segment their revenue streams clearly to comply once the October 1, 2026, date arrives, and this segmentation becomes essential because mixed offerings could trigger different tax treatments depending on the dominant category.
According to the amendment details, the narrowed VAT exemptions reduce the scope of previously exempt supplies, which means certain gaming-related services may now fall under standard VAT rules. People who follow fiscal policy updates note that these adjustments form part of a wider review of the gaming sector’s contribution to public finances, and the changes take effect simultaneously with the new tax tiers.
Implementation Timeline and Scope
The reform takes effect on October 1, 2026, which gives operators several months to adjust accounting systems and reporting procedures before the transition occurs. Legal references point to the Gaming Tax (Amendment) Regulations available through legislation.mt, and related guidance on VAT appears in Legal Notice 86 of 2026. Operators handling both land-based and remote platforms must prepare for the domestic-only application, which leaves their international player bases operating under the established 5% flat rate unchanged.
Figures from sector analyses reveal that Malta’s gaming industry has long balanced competitive tax conditions with regulatory oversight, yet this adjustment refines the treatment of locally sourced revenue without extending to foreign markets. Those who have studied similar fiscal updates across European jurisdictions recognize that domestic targeting often aims to capture value from local consumption while preserving attractiveness for global operators.
Broader Fiscal Context
This set of amendments integrates into ongoing refinements of Malta’s gaming tax regime, and the removal of the device levy simplifies compliance for venues that previously managed separate assessments on gaming machines. The tiered rates reflect distinctions between chance-based casino products and skill or betting elements, which creates clearer boundaries for tax calculation purposes. Observers note that narrowing VAT exemptions further aligns gaming services with standard fiscal treatment in other sectors.
Operators receive clear guidance through MGA fact sheets and the referenced legal notices, which detail how to classify services and report domestic revenue separately from international streams. The October 2026 start date allows time for system updates and internal audits, and the focus remains strictly on revenue derived from players located within Malta’s borders.
Conclusion
The transition to tiered gaming taxes under the Gaming Tax (Amendment) Regulations marks a targeted update to Malta’s fiscal approach for domestic gaming activity, with the 15% and 10% rates replacing the prior flat structure while eliminating the device levy and adjusting VAT exemptions. International operations stay outside the scope of these changes, and the October 1, 2026, implementation provides a defined timeline for compliance adjustments across the sector.